Pay by Bank for SME Payments
Why 2026 changed everything
This report breaks down what changed, what it costs (and saves), and where Pay by Bank does, and doesn't, make sense for your product.
Pay by Bank was ahead of its time. Until now.
The infrastructure is ready
Interface quality and coverage have improved substantially, instant SEPA transfers are now the default across the eurozone, and mandatory e-invoicing is turning invoices into ready-to-pay data. The obstacles that made Pay by Bank premature are disappearing one at a time.
Fees keep scaling
On a typical B2B invoice, the cost difference between a card payment and a bank transfer isn't marginal; it's a multiple. For platforms still charging or absorbing card-based fees, that gap is either a cost to manage or a margin to capture.
End users expect more
A wave of SME-focused accounting and finance platforms has scaled quickly across Europe, and as they did, they raised what customers expect an "accounting tool" to include. Increasingly, that means moving the money, not just recording it.
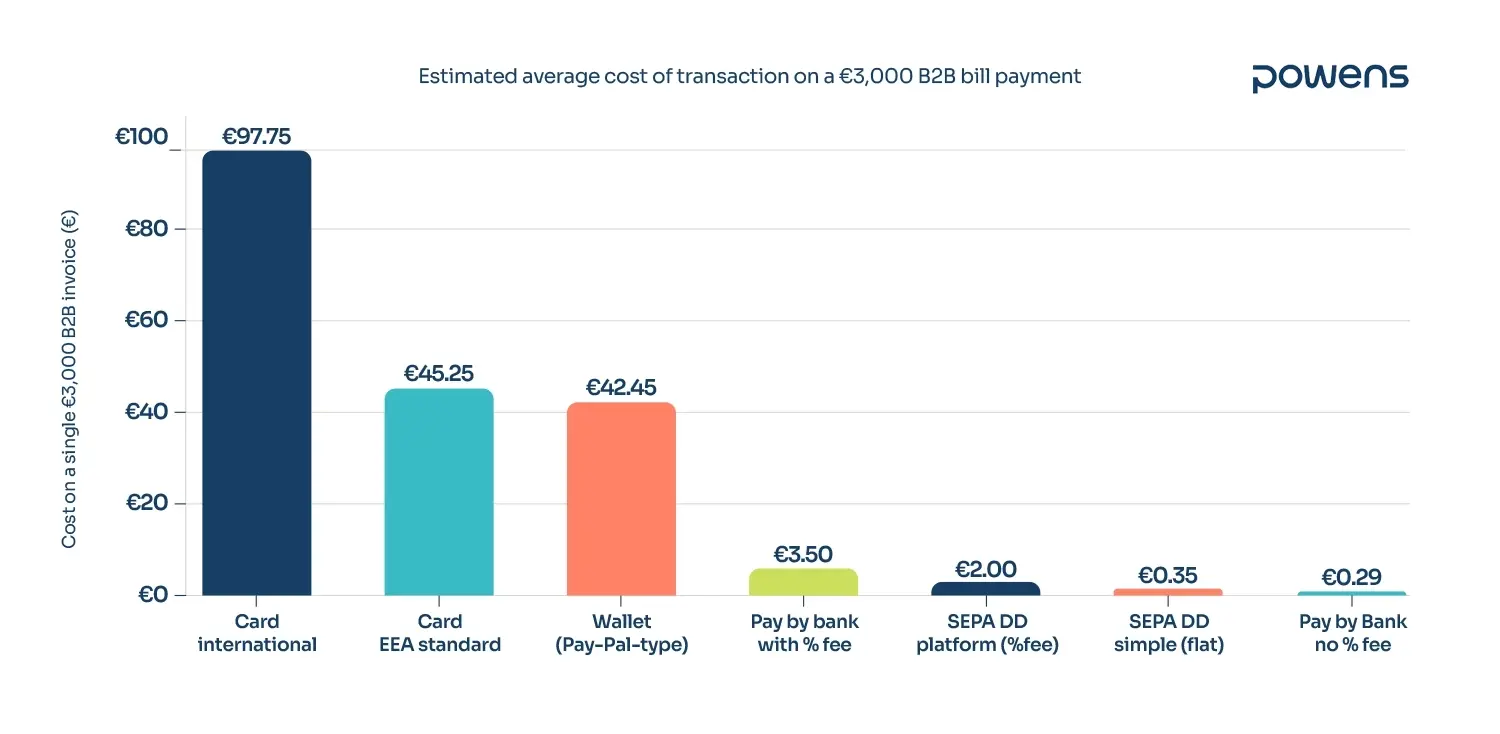
The economy finally
favors a method that’s cheaper and faster.
If you're deciding whether, and how, to bring Pay by Bank into your platform, this report lays out the data behind that decision: what's changed, what it costs, and where the real limits still are.
You've got questions, we've got answers
Pay by bank is a Payment Initiation Service (PIS) built on Open Banking that enables businesses to initiate a bank-to-bank payment directly from a customer’s account, with their explicit consent.
Powens is the Open Finance platform that helps financial institutions and fast-growing startups in Europe and Latin America automate complex financial operations: from data insights to payments, across credit, reconciliation, onboarding, cash management, property management, wealth management, retail banking, and cashback.
With real-time access to financial data in 12+ countries and a wide range of SEPA payment methods, Powens enables faster decisions, smoother customer journeys, and more scalable products.
©2026 Powens Group. All rights reserved. Privacy Policy